J.P. Morgan paints rosy picture for Philippines economy
MANILA, Philippines — Global investment bank J.P. Morgan expects the Philippine economy to expand by 5.3 percent this year and five percent in 2026, outpacing most of its Southeast Asian peers amid headwinds from global trade tensions and shifting monetary policy in the United States.
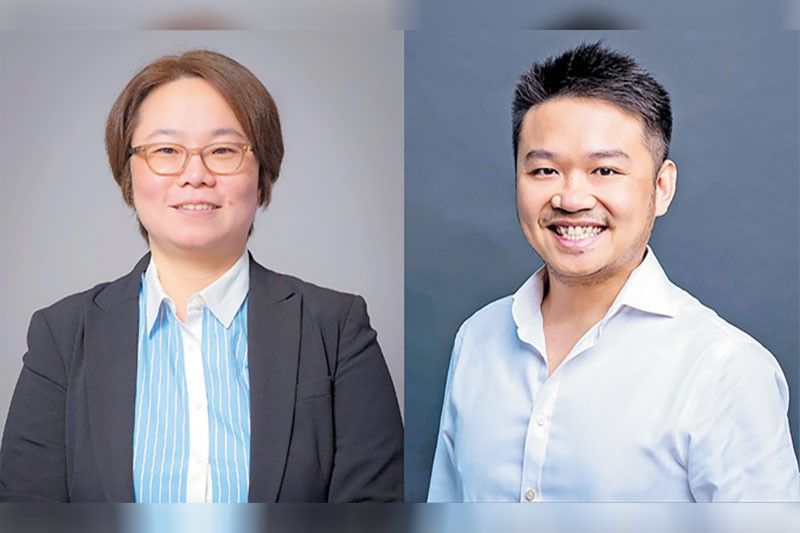
In an interview with The STAR, J.P. Morgan ASEAN equity strategist Khoi Vu said the Philippines’ relatively low dependence on exports makes it more resilient to external shocks compared to neighbors such as Thailand, Malaysia, Vietnam and Singapore, where exports account for as much as 70 percent of gross domestic product (GDP).
Vu said that several Association of Southeast Asian Nations (ASEAN) economies are highly exposed to exports, making them vulnerable to US trade policy and tariffs from an external perspective.
“By contrast, the Philippines’ export-to-GDP ratio is much lower, so the economy is relatively insulated. We are forecasting a GDP growth of 5.3 percent this year and around five percent next year, which is more resilient than peers.”
Vu noted that consumption and private investment will be the main growth drivers, supported by easing inflation, lower interest rates and improved consumer sentiment.
Jeanette Yutan, J.P. Morgan’s Philippines head of research, explained that their GDP forecast already takes into account the potential drag from reciprocal tariffs.
“If those effects are delayed or smaller than expected, then 5.3 percent could move up closer to 5.5 percent,” she said during the same interview.
The Philippine economy grew by 5.5 percent in the second quarter, bringing the first half average to 5.4 percent. The government is targeting a slightly higher growth rate of 5.5 to 6.5 percent this year.
Yutan stressed that upside risks exist, but much would depend on fiscal spending and the country’s ability to attract foreign direct investments.
J.P. Morgan expects full-year inflation to average at 1.5 percent before picking up modestly to 2.4 percent in 2026. With price pressures easing, the bank sees more room for the Bangko Sentral ng Pilipinas (BSP) to continue cutting rates.
“Inflation has come down sharply,” Vu said. “This gives the central bank room to cut rates. The BSP has cut three times this year, and we expect two more — one in December and possibly another in February 2026.”
Headline inflation eased to 1.5 percent in August, falling below the government’s two to four percent target range.
J. P. Morgan also expects the US Federal Reserve to begin a rate-cutting cycle in September, with four 25-basis-point reductions that could bring the Fed funds rate to 3.5 percent by early next year.
“This should weaken the dollar, which is positive for the peso and the BSP’s policy flexibility,” Vu added.
Against this backdrop, J. P. Morgan upgraded its outlook on Philippine equities from neutral to overweight earlier this year, citing easing price pressures, falling commodity costs and expectations of rate cuts.
“With easing inflation, falling commodity prices and rate cuts ahead, we upgraded the Philippines from neutral to overweight. We expect consumer sentiment and corporate earnings to revive,” Vu said.
Yutan said the bank expects corporate earnings growth of seven to nine percent this year, with a similar trajectory next year, making the country’s equities more attractive relative to ASEAN peers.
“Our overweight call means we expect better equity returns versus the rest of ASEAN, supported by lower rates, waning inflation and a stable peso,” she added.
Consumers and banks in focus
Yutan noted that private consumption — though slower post-pandemic at four to five percent growth — is expected to strengthen as disinflation boosts real wage growth.
“For the first time in three years, we’ll finally see real wage growth that is in positive territory,” she said. “If inflation stays low and government spending picks up, consumption growth could return to seven to nine percent.”
On the banking sector, J.P. Morgan remains constructive. While lower policy rates may compress net interest margins, Yutan said this would likely be offset by potential reserve requirement ratio cuts, healthy loan growth and robust asset quality.
“Return on equities are at 13 to 14 percent, the highest in the last decade, and should be sustained,” she said. “System non performing loan ratio remains below 3.5 to four percent, which is low given double-digit credit growth.”
She highlighted opportunities in consumer lending, citing the Philippines’ low household debt relative to ASEAN peers. “Structurally, the demographics are favorable, with a young population entering prime consumption years,” she said.
Key risks
Despite its positive outlook, J.P. Morgan flagged several risks that could weigh on growth and investor sentiment.
Vu said the biggest external risks remain US trade policy and Fed decisions. “If tariffs fuel US inflation and the Fed delays cuts, the BSP may have less room to ease,” he warned.
Another risk is the strength of US equities, which could divert capital away from emerging markets. Geopolitical shocks such as the Russia-Ukraine conflict could also push up commodity prices again, hurting the Philippines through inflation.
“While the Philippines is more resilient than peers, risks from global shocks are always present,” Vu said.
Overall, J.P. Morgan expects the Philippines to remain a relative bright spot in ASEAN, cushioned by strong domestic demand and monetary policy support.
The investment bank’s overweight call signals confidence that easing inflation, stable fundamentals and improving sentiment will bolster both growth and equities in the years ahead.






- Latest
- Trending